How to Use Your Superannuation to Invest in Land
Understanding the Self-Managed Super Fund (SMSF) Process
Could your superannuation be used for a land investment?
Many Australians have accumulated superannuation savings throughout their working lives. While most superannuation funds invest on behalf of their members, a Self-Managed Super Fund (SMSF) provides an alternative structure through which eligible individuals can manage their retirement investments.
An SMSF may be permitted to invest in certain types of land, property and investment trusts, subject to Australian superannuation legislation and the fund's governing documents.
Vertical Village is a cooperative land project in Bringelly, New South Wales. Prospective participants who already operate an SMSF, or are considering establishing one, may wish to investigate whether their fund could lawfully participate in the project.
Important: SMSF investment in Vertical Village is not automatically permitted. The project's legal structure, investment documents and the SMSF's individual circumstances must be independently reviewed before any SMSF money is accepted.
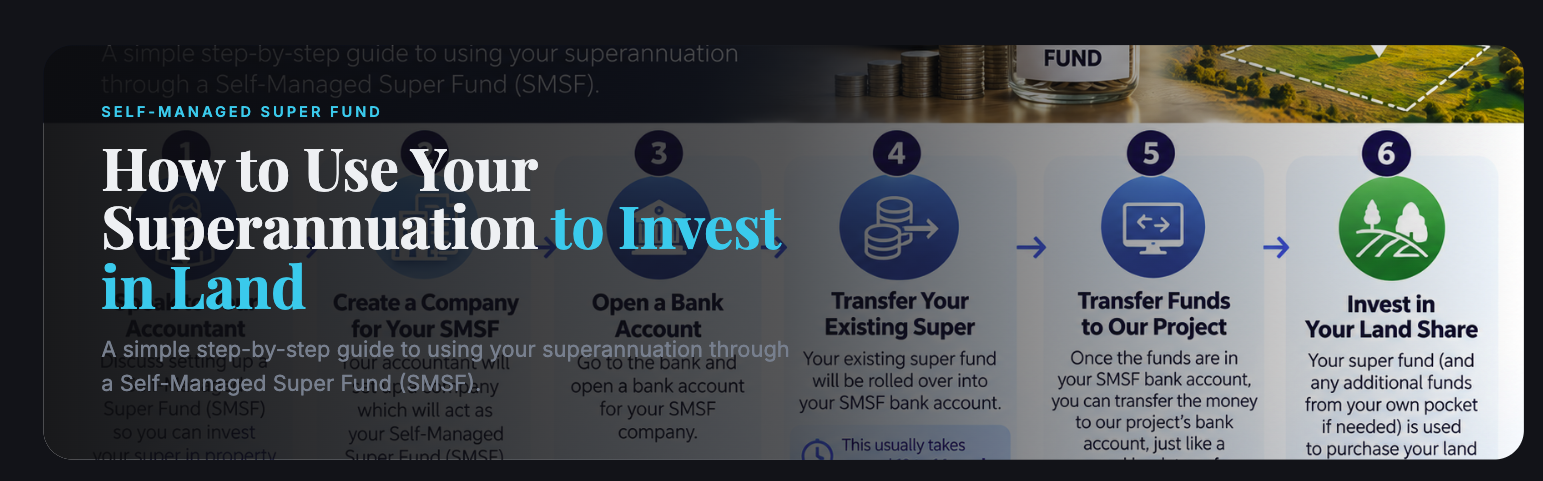
Six Steps from Accountant to Land Share
Speak to Your Accountant
Discuss setting up a Self-Managed Super Fund (SMSF) so you can invest your super in property.
Create a Company for Your SMSF
Your accountant will set up a company which will act as your Self-Managed Super Fund (SMSF).
Open a Bank Account
Go to the bank and open a bank account for your SMSF company.
Transfer Your Existing Super
Your existing super fund will be rolled over into your SMSF bank account.
Transfer Funds to Our Project
Once the funds are in your SMSF bank account, you can transfer the money to our project's bank account, just like a normal bank transfer.
Invest in Your Land Share
Your super fund (and any additional funds from your own pocket if needed) is used to purchase your land in our project.
The process starts with your accountant.
Transfer of existing super usually takes 12 to 14 weeks.
If your super fund balance is not enough, you can pay the remaining amount from your own funds (out of pocket).
Understanding the Process
Start by Speaking to Your Accountant and a Licensed SMSF Adviser
Your journey begins with professional advice, not with a payment to Vertical Village.
If you are considering using your superannuation for a land investment, your first step is to contact an accountant experienced in SMSF administration and a financial adviser appropriately licensed to provide SMSF advice.
Your advisers should help you understand:
- Whether establishing an SMSF is appropriate for your financial situation.
- How much superannuation you currently hold.
- The costs and responsibilities of managing your own super fund.
- Whether an investment in a cooperative land project could be legally permissible.
- Whether you have sufficient funds for the proposed investment and ongoing SMSF expenses.
- The investment risks, including possible delays, limited liquidity and potential capital losses.
- The effect of transferring your superannuation on your existing insurance and retirement arrangements.
An SMSF is not simply another bank account. It is a regulated superannuation trust established to provide retirement benefits.
Your action: Arrange an initial consultation and obtain independent advice before proceeding.
Establish Your Self-Managed Super Fund
If professional advice confirms that an SMSF is suitable, your accountant and SMSF establishment professionals can assist with the setup process.
An SMSF is a trust, not a company. However, many SMSFs use a specially established company as their corporate trustee.
A typical establishment process includes:
- Establishing the SMSF trust and preparing its trust deed.
- Registering a corporate trustee with ASIC, if that structure is selected.
- Appointing the SMSF members as directors of the corporate trustee, subject to eligibility requirements.
- Obtaining an Australian Business Number (ABN) and Tax File Number (TFN) for the SMSF.
- Registering the SMSF with the Australian Taxation Office (ATO).
- Preparing an appropriate written investment strategy.
- Completing the required trustee declarations and compliance documentation.
What happens next?
Once the SMSF has been properly established and registered, its trustees can arrange banking facilities and prepare for any eligible superannuation rollovers.
Your action: Work with your accountant to establish the fund and ensure its trustee structure, registration and documentation are correct.
Open a Dedicated SMSF Bank Account
After establishing the SMSF, the trustee will need a dedicated bank account for the fund. The account must be appropriately titled and operated for the SMSF. Where a corporate trustee is used, the account will generally identify the corporate trustee acting on behalf of the SMSF.
The bank may request:
- The SMSF trust deed.
- Corporate trustee registration details, where applicable.
- SMSF ABN and TFN information.
- Identification for trustees and authorised signatories.
- Other documentation required under the bank's policies.
This bank account is used to receive eligible rollovers and contributions, pay fund expenses and make authorised investments. SMSF money must remain separate from your personal money and the money of any other business or company.
Your action: Open and verify the SMSF bank account with your chosen financial institution.
Arrange the Rollover of Your Existing Superannuation
Once the SMSF is properly registered, eligible to receive rollovers and has an operational bank account, you can arrange to transfer eligible superannuation balances from your existing super fund. This process is called a superannuation rollover.
For example, if you currently have superannuation with a retail, industry or other complying super fund, you may be able to transfer some or all of your eligible balance to your SMSF.
Before requesting a rollover, check:
- Whether your existing superannuation benefits can be transferred.
- Whether you would lose insurance cover.
- Whether your existing fund has any restrictions or special benefits.
- Whether the SMSF is listed as eligible to receive rollovers.
- Whether enough money will remain available to meet your retirement and insurance needs.
How long does this take?
Allow sufficient time for establishing the SMSF, registering it with the ATO, opening its bank account and completing the rollover. For planning purposes, some people may allow approximately 12–14 weeks for the overall setup and transfer process, although this is not a standard or guaranteed timeframe.
Your action: Request the rollover through the appropriate superannuation process and confirm that the money has arrived in the SMSF bank account.
Review the Vertical Village Investment with Your Advisers
Before making any payment, obtain the relevant Vertical Village project documents and provide them to your independent SMSF advisers. Your accountant, licensed financial adviser and SMSF solicitor should review the proposed investment.
This review must establish:
- The precise legal interest that the SMSF would acquire.
- Whether the investment is in land, units in a trust or another type of financial interest.
- Whether the SMSF is permitted to acquire and hold that interest.
- Whether the investment satisfies the sole purpose test and the SMSF's investment strategy.
- Whether related-party, in-house asset or non-arm's-length transaction rules apply.
- Whether any proposed future subdivision or allocation arrangement is compatible with SMSF rules.
- Whether the investment is appropriately valued and documented.
- Whether the SMSF has sufficient liquidity for its other obligations.
- Whether the investment can be sold or transferred and what restrictions apply.
This is a critical stage. Not every property-related investment is suitable or lawful for an SMSF.
Your action: Obtain confirmation from appropriately qualified advisers that the specific proposed investment can proceed lawfully.
Complete the Investment Documents
If the proposed investment is legally permissible and your SMSF trustee decides to proceed, the next stage is completing the required project documentation. Depending on the investment structure, this may include:
- An investment application in the correct SMSF trustee name.
- The relevant project agreement or unit subscription documents.
- Identification and verification of the SMSF trustee.
- SMSF registration and trustee details.
- Applicable legal and financial disclosures.
- Independent professional approvals and any other required documents.
The investment documents must correctly identify the legal investor. For example, where an SMSF uses a corporate trustee, the investor may be recorded as:
[Corporate Trustee Pty Ltd] ATF [Your SMSF Name]
The final wording should be confirmed by the fund's solicitor.
Your action: Ensure all investment documents have been reviewed, approved and properly executed before transferring any funds.
Transfer Approved Investment Funds from Your SMSF
Once all legal checks, documentation and approvals are complete, the SMSF trustee may arrange payment for the authorised investment. The payment would generally be made from the SMSF's dedicated bank account to the verified bank account specified in the approved investment documents.
Although the electronic banking process may look similar to an ordinary bank transfer, an SMSF payment is not a personal transaction. The trustee must ensure that:
- The investment has been properly authorised.
- The receiving account has been independently verified.
- The payment matches the investment agreement.
- The transaction is recorded in the SMSF's accounting records.
- The SMSF receives appropriate evidence of its investment interest.
Do not transfer SMSF money to an individual's personal account or make an advance payment while the legal investment structure remains unresolved.
Your action: Arrange the authorised payment and retain the transaction confirmation, investment agreement and official receipt.
What If Your SMSF Balance Is Not Enough?
Suppose the proposed investment requires $190,000, but your SMSF has only $150,000 available. You may wonder whether you can contribute the remaining $40,000 from your personal savings.
It is important to understand that personal money and SMSF money cannot simply be combined in a single personal land purchase. Possible arrangements may include:
Option A — Make an eligible contribution to your SMSF
Subject to contribution limits, eligibility rules and professional advice, you may be able to contribute personal money into your SMSF. The SMSF could then potentially make the investment using its own funds.
Option B — Consider a separately documented ownership arrangement
In some circumstances, a legally structured co-investment may be possible. However, related-party rules, title arrangements, investment restrictions and the nature of the project must be carefully reviewed.
Option C — Invest personally instead of through an SMSF
If the proposed SMSF investment is not permitted or appropriate, you may consider whether a separate personal investment is suitable. Any personal investment must remain legally distinct from an SMSF investment unless an appropriately advised structure permits otherwise.
Your action: Discuss any funding shortfall with your advisers before making additional payments.
Receive Your Investment Confirmation and Maintain SMSF Records
After the investment has been validly accepted and the required payment has been received, the SMSF trustee should receive documentation confirming its investment interest. Depending on the final legal structure, this could include:
- An official payment receipt.
- A completed investment agreement.
- A unit holding confirmation or certificate, where applicable.
- Details of the SMSF's recorded investment.
- Information on future reporting and distributions, if any.
- Relevant updates about the project's progress.
Your SMSF accountant will generally need these records for the fund's annual accounts, valuation requirements and independent audit. The SMSF trustee remains responsible for managing the investment in accordance with superannuation law.
Your action: Keep all documentation and arrange ongoing accounting, valuation, reporting and compliance.
Your SMSF Investment Journey at a Glance
| Stage | What happens | Who is responsible? |
|---|---|---|
| 1. Professional advice | Assess SMSF suitability and investment rules | Accountant and licensed adviser |
| 2. SMSF establishment | Establish the trust and trustee structure | SMSF professionals |
| 3. Banking | Open the SMSF bank account | SMSF trustee and bank |
| 4. Rollover | Transfer eligible existing superannuation | Existing fund and SMSF trustee |
| 5. Investment review | Assess the proposed Vertical Village investment | Independent advisers and solicitor |
| 6. Documentation | Complete legally approved investment agreements | SMSF trustee and project |
| 7. Payment | Transfer authorised SMSF investment funds | SMSF trustee |
| 8. Confirmation | Obtain receipts and investment records | Project and SMSF trustee |
| 9. Ongoing management | Maintain records, valuations, reporting and compliance | SMSF trustee and professionals |
Important Things to Understand
Your SMSF Money Remains Retirement Money
Even if you establish an SMSF and become a director of its corporate trustee, the fund's assets do not become your personal spending money. SMSF investments must be maintained for lawful retirement purposes. You generally cannot use SMSF-owned residential property or land for your own private benefit before meeting the applicable legal requirements.
An SMSF Is Not Suitable for Everyone
SMSFs can involve establishment expenses, annual accounting and audit fees, tax reporting, trustee responsibilities and significant regulatory obligations. You should compare the costs and risks of an SMSF with remaining in your existing superannuation fund.
Land Investment Involves Risks
Land investments may involve changes in market value, planning delays, rezoning uncertainty, development costs and difficulty selling an interest quickly. A proposed future lot or land allocation is not necessarily an existing subdivided title. Any future subdivision remains subject to the relevant planning, survey and council approvals.
Returns and Access to Funds Are Not Guaranteed
Any potential distribution, dividend, capital gain or future exit arrangement must be assessed against the actual project documents. Investment returns may be lower than expected, delayed or negative. Superannuation investments are subject to preservation and access rules.
Independent Advice Is Essential
The project operator cannot determine whether an SMSF investment is appropriate for an individual investor. Your licensed financial adviser, accountant and solicitor should independently assess your circumstances and the proposed investment.
Frequently Asked Questions
What to Do Next
Start with Your Accountant and Licensed SMSF Adviser
If you are exploring the possibility of investing in Vertical Village through your superannuation, begin by obtaining independent professional advice. Once your advisers have assessed whether an SMSF is suitable for you, they can review the project's legal documents and determine whether the proposed investment is permissible.
110 Carr Road, Bringelly NSW 2556
Important Disclaimer
This information is provided for general educational purposes only and does not constitute personal financial advice, financial product advice, legal advice or tax advice. Vertical Village does not recommend establishing an SMSF, transferring existing superannuation or investing retirement savings in the project. SMSF investments are regulated under Australian superannuation legislation. The legality and suitability of any proposed investment depend on the SMSF's circumstances, the investment structure and applicable law. No statement on this page should be interpreted as confirmation that Vertical Village is an eligible SMSF investment. Prospective investors must obtain independent advice from appropriately licensed and qualified professionals before making any financial commitment. All investments carry risk, including the possible loss of capital.